


High-yield bonds defy expectations amid market shocks
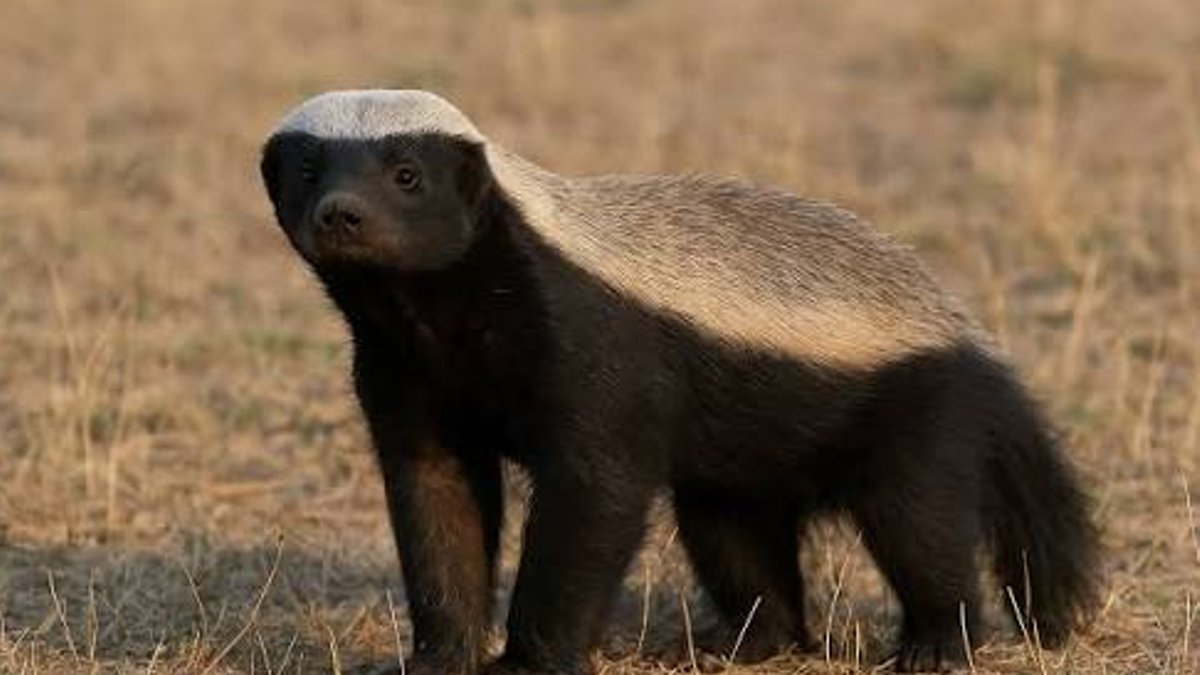
The US high-yield bond market has endured more disruptions than most investors anticipated. Oil price collapses, Federal Reserve interest rate hikes, pandemics, wars, and inflation spikes have all failed to spark the widespread credit crisis many expected. Instead, spreads widened temporarily before tightening again, as if the market dismissed each disruption. The comparison to the honey badger meme—“Honey badger don’t care”—captures this defiant resilience.
This durability becomes clear when examining high-yield spreads over the past decade. Every major shock prompted a repricing of risk, but few led to lasting damage. The recession forecasted for 2022 never materialized, corporate earnings remained stable, and default rates stayed controlled. Even the Ukraine conflict, which disrupted energy markets, did not ignite a systemic credit crisis. The market absorbed the impact, adjusted, and continued operating.
The market’s strength stems partly from structural changes. In 2007, BB-rated bonds, considered the higher-quality segment of high yield, made up about 38% of the US high-yield index. By 2026, that share had climbed to 60%. Over the same period, bond durations shortened, secured issuance increased, and refinancing replaced acquisitions as the primary use of proceeds. The composition of the index has grown safer, even as private credit and leveraged loans absorbed many riskier borrowers that once depended on the high-yield cash market.
Read Also: UK Debt Strategy Mirrors British Airways’ Avios Devaluation Tactics
Private credit’s growing cracks force borrowers back
This evolution carries risks, however. Private credit funds have faced increasing strain, particularly in technology-related sectors. Some funds, burdened by lower-quality portfolios or concentrated issuer exposure, have struggled to refinance weaker borrowers. As a result, more companies that previously relied solely on private loans are now returning to the high-yield market for funding. This shift indicates private credit’s capacity may be diminishing.
A second key factor keeping spreads tighter than expected is the imbalance between supply and demand. New high-yield issuance has been limited in recent years, partly because borrowers have shifted to loans or private credit. Meanwhile, demand for yield remains robust, supported by higher base rates. Investors now earn returns from both spreads and carry, making all-in yields appealing even as spreads narrow.
Energy and stimulus created temporary market distortions
Energy and the pandemic stand out as exceptions. Energy was the largest component of the high-yield index when the 2020 crash occurred, distorting overall performance. Without this sector, spreads would have recovered even more quickly. The pandemic’s impact was also unique: fiscal stimulus and monetary support prevented a worse default wave, though these measures later contributed to inflation and triggered the 2022 widening episode. Unlike other shocks, the pandemic’s recovery was driven more by policy than economic fundamentals, demonstrating how external interventions can temporarily reshape market behavior.
Read Also: Airbus creates 480 jobs in North Wales
The honey badger analogy remains fitting because the market does react, every shock causes spreads to widen. However, the critical difference is that these reactions rarely escalate into broader crises. The market absorbs disruptions, reassesses risks, and continues functioning. Whether this resilience persists depends on future developments, including sustained high interest rates or unexpected disruptions.
The US 10-year Treasury yield hovers around 5%, which could strain corporate earnings and refinancing needs. Raised oil prices may further pressure growth. For now, the high-yield market remains unbroken, adapting to each challenge without collapsing. The question is no longer whether the next shock will arrive, but whether it will finally disrupt the established pattern.


